Anton Klieshnin ,
Analyst at the TP Department
Table of Contents
The 2025 transfer pricing reporting campaign is already in its active phase, and although the filing deadline may seem far away, it is worth preparing right now.
Identification of Controlled Transactions
We have updated the diagram in accordance with the latest changes in tax legislation, which will help you independently determine whether your transactions with a non-resident counterparty fall under Art. 39 of the Tax Code of Ukraine (hereinafter – TCU) and are controlled, or whether they require an adjustment to the financial result before tax in accordance with sub-clauses 140.5.4, 140.5.51, 140.5.6, 140.5.7 of clause 140.5 of Art. 140 of the TCU. Proper analysis of these conditions directly affects how a company conducts transfer pricing and reports to supervisory authorities.
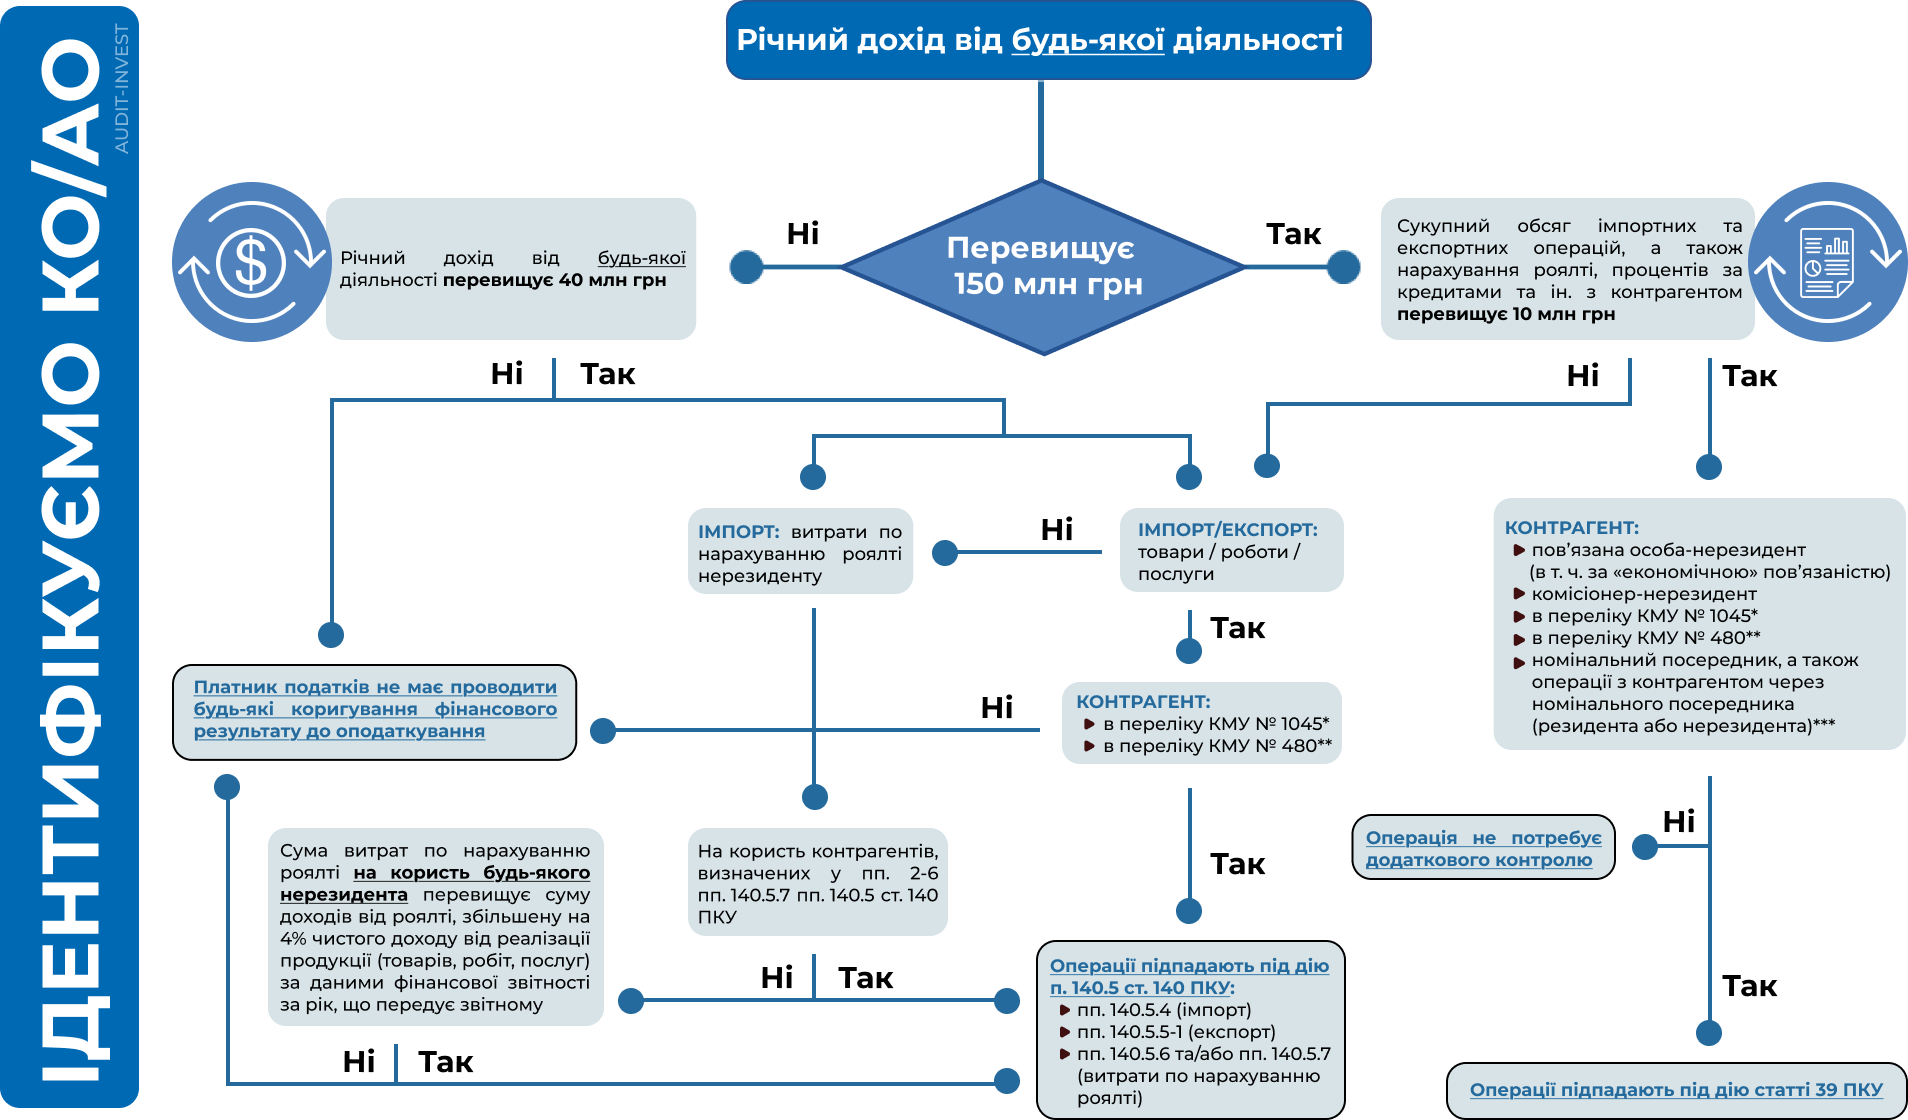
*https://zakon.rada.gov.ua/laws/show/1045-2017-%D0%BF
**https://zakon.rada.gov.ua/laws/show/480-2017-%D0%BF
***definition of a nominal intermediary within the meaning of sub-clause 39.2.1.5 of sub-clause 39.2.1 of clause 39.2 of Art. 39 of the Tax Code of Ukraine
Important:
A nominal intermediary can be either a resident of Ukraine or a non-resident.
Legal entities are considered related in the event of:
- direct or indirect ownership by one entity of 25% or more of the statutory capital of another entity,
- the same legal entity or individual directly and/or indirectly owns corporate rights in each such legal entity in the amount of 25 percent or more,
- exercising effective control over entities in the absence of formal participation in the capital of such entities,
- the ultimate beneficial owner (controller) of the legal entities is the same individual,
- “economic relatedness” with non-residents of any country (applies to transactions from 01.2025).
For details on how to identify “economic relatedness,” see the news article Economic Relatedness – A New TP Term from 01.01.2025.
Controlled transactions also include business transactions conducted between a non-resident and its permanent establishment in Ukraine, which are omitted from the diagram because reaching the value threshold of UAH 150 million in annual income from all activities is not mandatory with respect to such transactions.
Business transactions between a non-resident and its permanent establishment in Ukraine are recognized as controlled if their volume, determined under accounting rules, exceeds UAH 10 million (net of indirect taxes) for the relevant tax (reporting) year.
Practical Steps
Step 1. Prepare the Report on Controlled Transactions
- ✔Prepare a list of all controlled transactions
- ✔Complete the Report on Controlled Transactions
- ✔Submit the Report on Controlled Transactions electronically (by October 1 of the year following the reporting year)
- ✔If the taxpayer is a member of a multinational enterprise (MNE) group and carried out controlled transactions during the reporting year — submit the corresponding Notification on Participation in an MNE Group
Step 2. Prepare Transfer Pricing Documentation
- ✔Conduct a functional analysis of the parties
- ✔Select and justify the transfer pricing method
- ✔Collect comparable data/prices/transactions
- ✔Calculate the arm’s length price/profitability range
- ✔Compile the TP documentation (must be finalized by the filing date of the Report)
- ✔Verify compliance with the arm’s length principle (if necessary – make an adjustment to the financial result in the corporate income tax return)
Step 3. Assess Risks and Liability
- ✔Failure by a taxpayer to submit the Report on Controlled Transactions – fine of 300 subsistence minimum amounts (for 2025 – UAH 908,400)
- ✔Failure to submit documentation upon request of the STS – fine of 3% of the controlled transaction amount, but not more than 200 subsistence minimum amounts (for 2025 – up to UAH 605,600)
- ✔Failure by a taxpayer to submit a notification on participation in an MNE group – fine of 100 subsistence minimum amounts (for 2025 – UAH 302,800)
- ✔Non-compliance with the arm’s length principle – additional assessment of corporate income tax, constructive dividends
If your foreign economic transaction falls under sub-clause 140.5.4 and/or 140.5.5-1 of clause 140.5 of Art. 140 of the TCU (export / import of products), you must:
1) EITHER increase the financial result before tax by 30% of the cost of purchased/sold goods, including non-current assets (except for right-of-use assets under lease agreements), works, and services (except for transactions specified in clause 140.2 and sub-clause 140.5.6 of clause 140.5 of Art. 140, and transactions recognized as controlled in accordance with Art. 39 of the Tax Code of Ukraine);
2) OR substantiate the amount of such expenses/income at prices determined under the arm’s length principle in accordance with the procedure established by Art. 39 of the Tax Code of Ukraine, but without submitting a report on controlled transactions (Prepare TP Documentation).
If your foreign economic transaction falls under sub-clause 140.5.6 of clause 140.5 of Art. 140 of the TCU (royalties paid to any non-resident), you must:
1) EITHER increase the financial result before tax by the amount of royalty expenses (except for transactions recognized as controlled in accordance with Article 39 of the Tax Code of Ukraine) in favor of a non-resident (including a non-resident registered in the states (territories) specified in sub-clause 39.2.1.2 of sub-clause 39.2.1 of clause 39.2 of Art. 39 of the Tax Code of Ukraine) exceeding the amount of royalty income increased by 4% of net revenue from sales of products (goods, works, services) according to financial statements for the year preceding the reporting year;
2) OR substantiate the amount of such expenses at prices determined under the arm’s length principle in accordance with the procedure established by Art. 39 of the Tax Code of Ukraine, but without submitting a report on controlled transactions.
If your foreign economic transaction falls under sub-clause 140.5.7 of clause 140.5 of Art. 140 of the TCU (royalties in favor of specified counterparties), you must:
Increase the financial result before tax by the amount of royalty expenses in full if royalties are accrued in favor of counterparties specified in sub-clauses 2–6 of sub-clause 140.5.7 of clause 140.5 of Art. 140 of the TCU, in particular in favor of:
- a non-resident who is not the beneficial (actual) recipient (owner) of the royalty, except where the beneficial owner (actual owner) granted the right to receive the royalty to other persons;
- a non-resident with respect to intellectual property objects rights to which first arose with a resident of Ukraine;
- a non-resident who is not subject to taxation regarding royalties in the state of which they are a resident;
- a person who pays tax as part of other taxes, except for individuals taxed under the procedure established by Section IV of the Tax Code of Ukraine (who are on the simplified taxation system);
- a legal entity that, in accordance with the Tax Code of Ukraine, is exempt from paying this tax or pays this tax at a rate other than that established in clause 136.1 of Art. 136 of the Tax Code of Ukraine.
Constructive Dividends: How to Avoid Tax Risks
Constructive dividends (in the area of international taxation and TP) arise if the terms of controlled transactions do not comply with the arm’s length principle.
According to sub-clause 14.1.49 of clause 14.1 of Art. 14, the following are treated as dividends for tax purposes:
- the amount of overstatement of the taxpayer’s expenses beyond the amount determined in compliance with the arm’s length principle;
- the amount of understatement of the taxpayer’s income below the amount determined in compliance with the arm’s length principle.
If the terms of controlled transactions do not comply with the arm’s length principle, the resident is required to additionally withhold non-resident income tax of 15% from the amount that does not comply with the specified principle (unless otherwise provided by an international treaty).
Important:
Constructive dividends may not arise provided there is a thorough analysis of international double taxation treaties (Conventions), in particular Article 10 of the relevant Convention. The provisions of this article may apply to income whose taxation corresponds to the term “dividends” defined in the relevant provisions of the international treaty (Convention).
CbC reporting (Country-by-Country reporting) in Ukraine became mandatory on July 4, 2024, and is aimed at increasing the tax transparency of multinational enterprise groups. It enables tax authorities to obtain detailed information on the allocation of the group’s economic activity across different jurisdictions. The report is submitted annually by the parent company in its country of registration, after which the relevant information is exchanged with tax authorities of other states where group companies are present.
The report is submitted by December 31 of the year following the reporting year. Accordingly, the report for 2025 must be submitted by December 31, 2026.
The primary obligation to submit a CbC report falls on the parent company of an international group, which is responsible for consolidating the financial and operational metrics of all constituent entities if the total consolidated group revenue exceeds €750 million.
We remind taxpayers of the need for timely submission of reports on controlled foreign companies (CFC) in accordance with the requirements of the TCU.
The Tax Code of Ukraine provides for the following penalties (clause 120.7 of Art. 120 of the TCU):
- for failure to submit a CFC report – 100 subsistence minimum amounts for an able-bodied person (UAH 302,800 for 2025);
- for late submission of a CFC report – 1 subsistence minimum amount for an able-bodied person (UAH 3,028 for 2025) for each calendar day of failure to submit, but not more than 50 such amounts;
- for failure to submit a Notification on changes in control status – 300 subsistence minimum amounts for an able-bodied person for each such fact (UAH 908,400 in 2025).
On May 9, 2024, the Law of Ukraine No. 3706-IX was adopted, introducing amendments to the transitional provisions of the TCU and suspending the application of penalties for violations provided for in paragraphs one through eight of clause 120.7 of the TCU (specifically those concerning CFC reporting) for the duration of martial law and for six months after its termination or abolition.
At the same time, it should be noted that this does not relieve taxpayers of the obligation to report on CFCs itself, but is merely a temporary deferral of liability for violations. This means that after the end of martial law, controlling persons will have only six months to submit reporting for 2022–2025 all at once.
Thus, this is not a complete cancellation of liability, but the introduction of a transitional period for taxpayers.
Penalties for the 2025 Reporting Year
For violations of legislation on transfer pricing, for the 2025 reporting year the following penalties are provided (clauses 120.3 – 120.5 of Art. 120 of the TCU):
| Violation | Penalty (2025) |
|---|---|
| Failure to submit TP documentation | up to UAH 605,600 (3% of the controlled transaction amount, but not more than 200 subsistence minimums) ; |
| Failure to provide the Report on Controlled Transactions, global TP documentation (master file) | UAH 908,400 (300 subsistence minimums) ; |
| Failure to include information in the submitted Report on Controlled Transactions about all controlled transactions carried out during the reporting period | up to UAH 908,400 (1% of the amount of controlled transactions undeclared in the submitted Report, but not more than 300 subsistence minimums) ; |
| Failure to submit a notification on participation in a multinational enterprise (MNE) group | UAH 302,800 (100 subsistence minimums) ; |
| Failure to submit a Country-by-Country Report of an MNE group (CbC) | UAH 3,028,000 (1,000 subsistence minimums) ; |
| Failure to include constituent entity information in the submitted Country-by-Country Report of an MNE group (CbC) | up to UAH 3,028,000 (1% of the amount of revenue of the MNE group member not reflected in the Report, but not more than 1,000 subsistence minimums) ; |
| Providing inaccurate information regarding a member of an MNE group in the Country-by-Country Report (CbC) | UAH 605,600 (200 subsistence minimums). |
Please note:
Payment of these fines does not relieve taxpayers of the obligation to prepare and submit the relevant report, documentation, and/or notification.
Advance preparation will minimize risks during the submission of Reports and the drafting of relevant Documentation, helping you confidently conclude the 2025 TP reporting campaign.
Audit Invest will help: screening of transactions with non-residents, Report on Controlled Transactions, and a complete transfer pricing documentation package.